From FT yesterday:
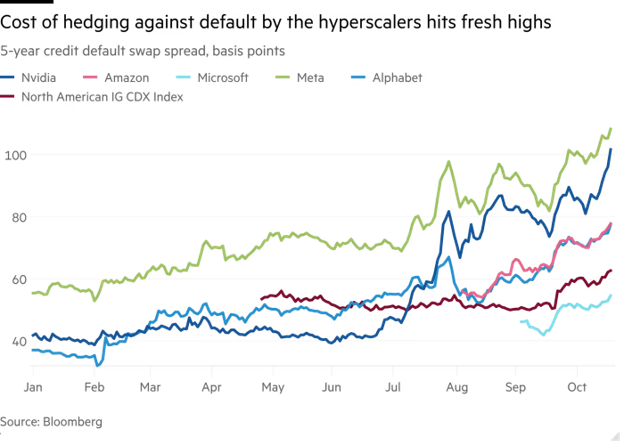
These are the large players in the AI boom; consider smaller players also involved in the AI boom:
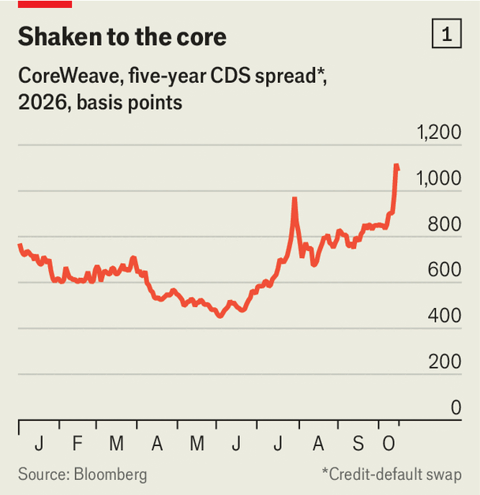
Credit markets are coming for CoreWeave. The price of a five-year bond issued by the “neocloud”, which rents out data-centre capacity for artificial-intelligence models, has fallen by 16% since July. The bond’s yield is now 15%—a level associated with companies in financial distress—up from 10% in July. The price of credit-default swaps offering insurance against a CoreWeave default implies that the probability of the company being unable to service its debts in the next five years has risen above 60% (see chart 1).
Investors increasingly worry that the companies at the heart of the AI boom will be unable to generate the cashflows necessary to service their vast debts. These concerns have spilled over from credit markets to cause a wobble in the stock market, too: having fallen sharply, the tech-heavy NASDAQ index is now back to where it was in mid-May. Investors are pricing in a debt stock that is getting bigger, more opaque—and increasingly risky.
This all leads to the $5.5 trn (by 2030) question – can borrowing really outstrip cash flow as much as required to hit planned capex spending?