Key indicators followed by the NBER Business Cycle Dating Committee, as well as alternative indicators:
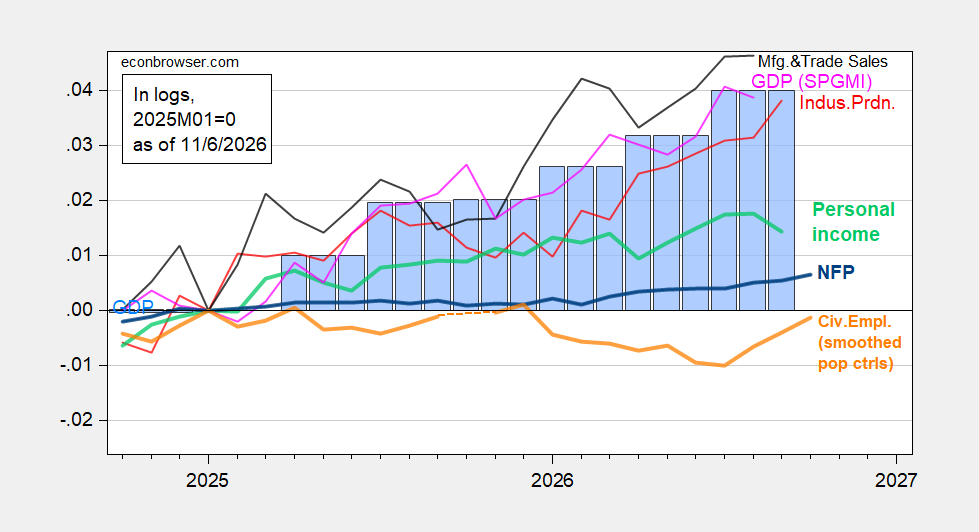
Figure 1: NFP employment (bold blue), civilian employment with smoothed population controls (bold orange), industrial production (red), personal income excluding current transfers in Ch.2017$ (bold light green), manufacturing and trade sales in Ch.2017$ (black), and monthly GDP in Ch.2017$ (pink), GDP (blue bars), all log normalized to 2025M01=0. Source: BLS via FRED, BLS, Federal Reserve, BEA 2026Q3 advance release, S&P Global Market Insights (nee Macroeconomic Advisers, IHS Markit) (10/2/2026 release), and author’s calculations.
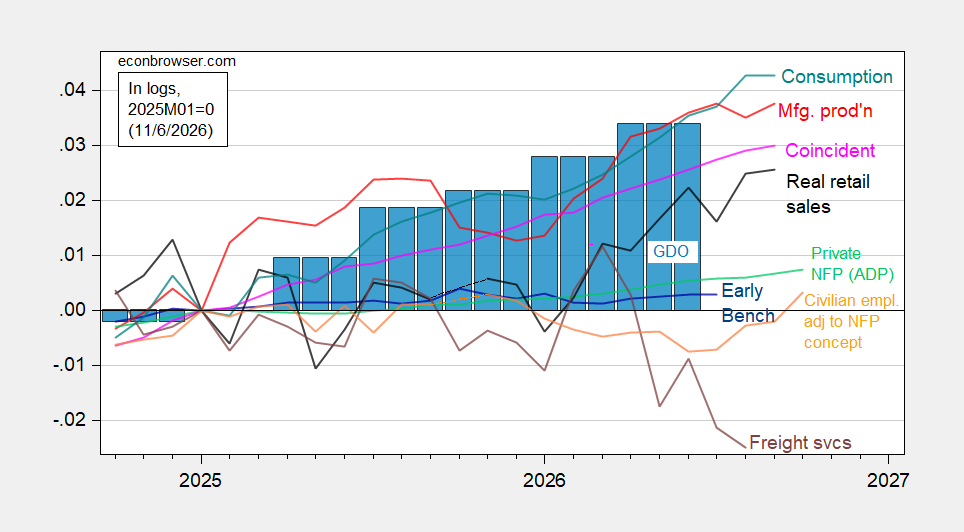
Figure 2: Civilian employment adjusted to NFP concept smoothed population controls, using experimental controls for 2025 (bold orange), manufacturing production (red), ADP private nonfarm payroll employment (light green), real retail sales, CPI deflated (black), freight services indexes (brown), and coincident index in Ch.2017$ (pink), GDO (blue bars), all log normalized to 2025M01=0. Source: BLS, ADP via FRED, Philadelphia Fed, Philadelphia Fed, Bureau of Transportation Statistics, Federal Reserve via FRED, BEA 2026Q3 advance release, and author’s calculations.
All measures of employment (BLS CES, BLS CPS, and ADP) are now rising, in contrast to 2026H1, although not at the pace of output. However, consumption and retail sales were flat in September, while personal income fell.
Other indicators of the labor market:
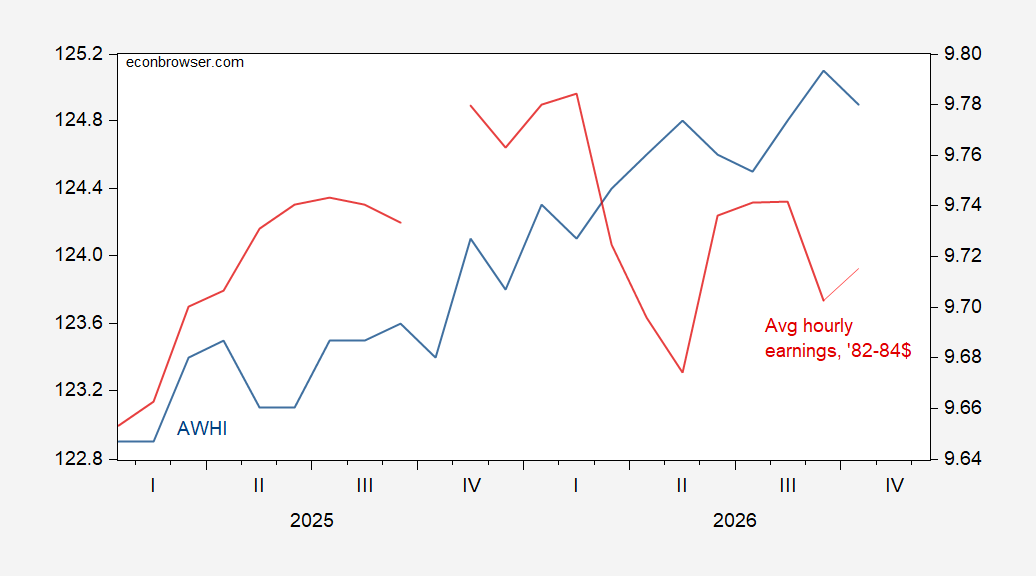
Figure 3: Aggregate weekly hours index (blue, left log scale), average hourly earnings in 1982-84$ (red, right scale). October 2026 average hourly earnings observation is based on CPI nowcast. Source: BLS, Cleveland Fed, and author’s calculations.