Using a plain vanilla term spread model (spread, short rate), what remains? From notes for tomorrow’s lecture.
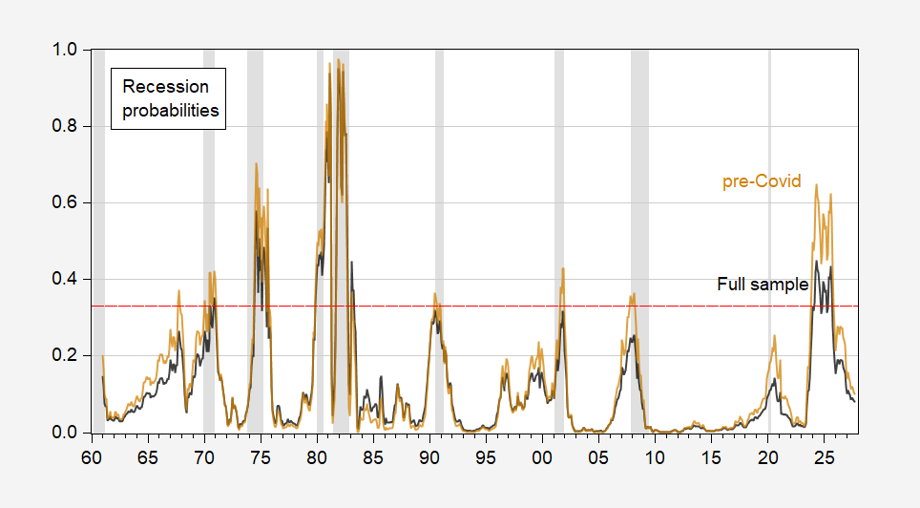
Figure 1: Estimated recession probabilities from probit on 10yr-3mo term spread, short rate over 1960-2018 (brown), over full sample (black). Red dashed line at 33%. NBER defined peak-to-trough recession dates shaded gray. Source: author’s calculations, NBER.
Using a 33% threshold and the pre-2018 sample, the term spread catches every post-1960 recession (taking the pandemic recession was not a typical recession), but gives the false positive for 2024. The full sample regression (assumes no recession appears by 2026M08) no longer catches the 1990-91, 2001, and 2007-09 recessions, and still provides a false positive for 2024.
In other respects, the full sample regression is less successful; the pseudo-R2 drops from 0.30 to 0.25.