Over $116/bbl.
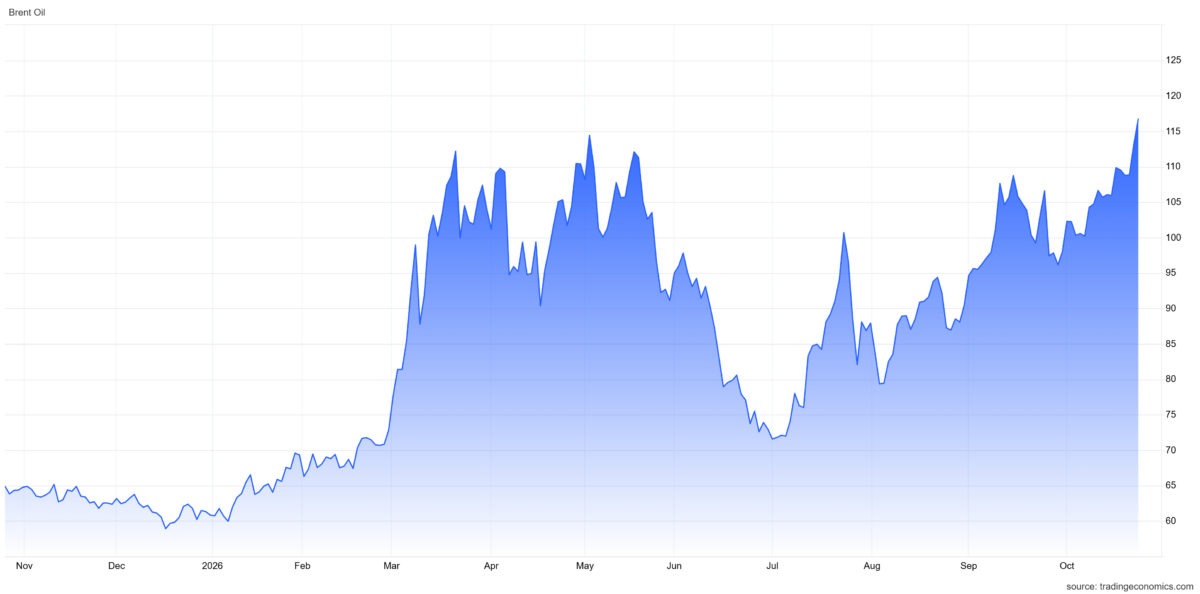
One can decompose the futures price increase into an pure expected price change, and risk premium. Robin Brooks “What’s Priced into Brent at $117?
A big risk premium has gotten priced in anticipation of a return to a “hot” war” argues that it’s largely due to risk premium increase — perhaps excessive — associated with a much signalled resumption of a “hot” war post-midterms.
Brooks bases his argument on the experience of previous supply reduction and the little change in far dated futures, and the logic makes sense. However, there have been some (big) surprises in this entire experience (including the sheer incompetence in war planning and strategic (presidential) decisionmaking), so it might be understandable that markets might place greater weight on larger disruptions than than occurred earlier.