Motio Research‘s measure is down 1.2% relative to May, but flat relative to July.
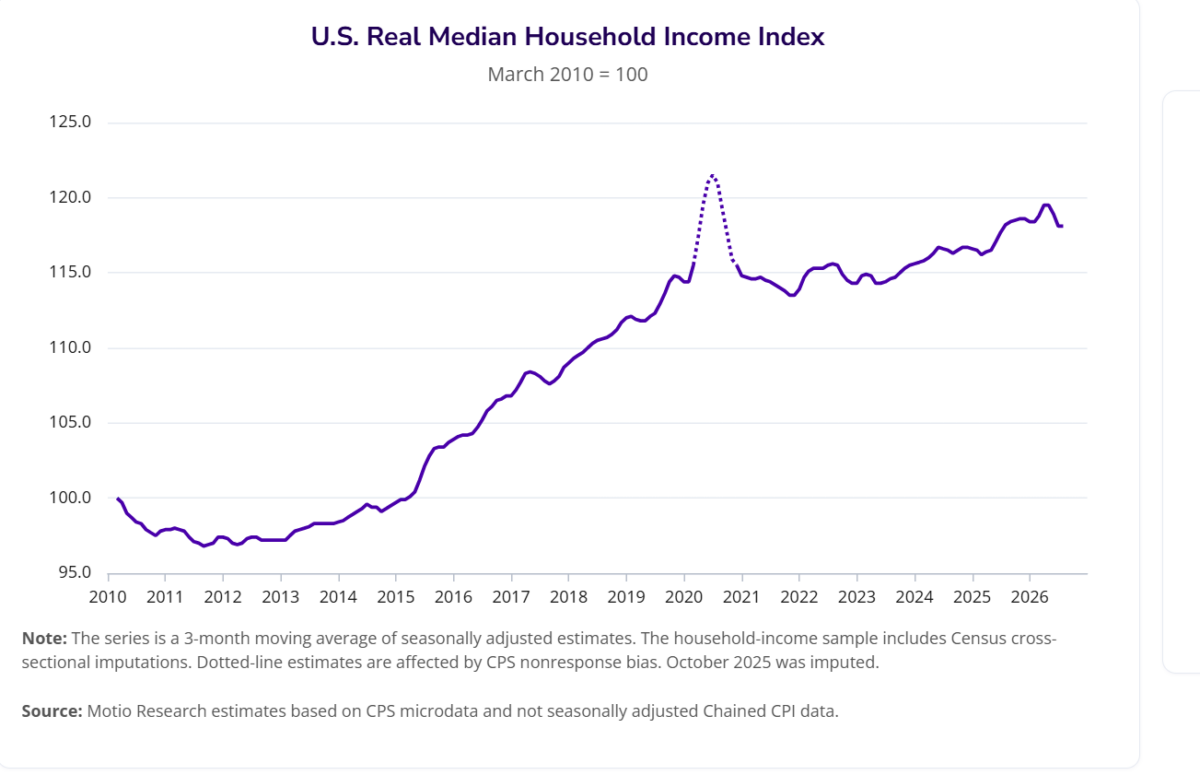
Note that the nominal income is also down 0.3% relative to May.
Their household-income momentum index, a recession signal, is down:
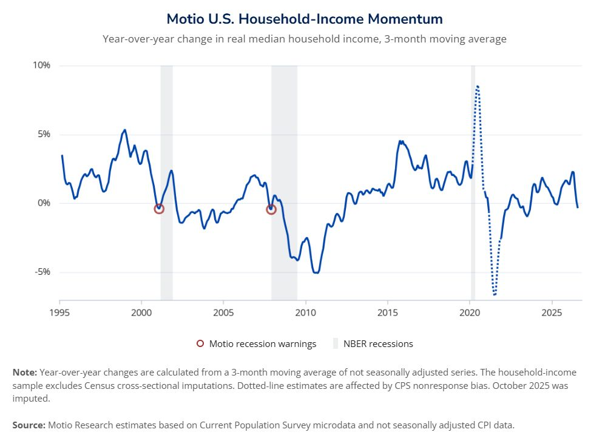
A description of this index is discussed in this post. According to their rule, we would need another two consecutive negative readings in order to trigger a “recession warning”; we’re just at a candidate contraction call.
interesting Motio chart. Eyeballing the data I get the following observations:
2010-2015–stagnation
2016–4% rise
2017-2020–11% rise
2021-2024–stagnation
2025-2026–3% rise
Pretty interestin.
There were a couple of negative momentum readings in 2023 and 2025 which have not (yet) led to recession calls from the NBER. The index is compounded of several factors, including wages, employment and inflation. One difference between those two earlier episodes and now is that employment was growing better then than now:
https://fred.stlouisfed.org/graph/?g=1YQsJ
Labor dynamism has also declined, with openings and hires both lower:
https://fred.stlouisfed.org/graph/?g=1YQuL
In the earlier recent episodes, inflation, rather than (nominal) wages or employment, was the primary problem. Now, we have a problem with all three. In the 2023 episode, external factors were mainly responsible for inflation while policy aimed at job an income growth. Now policy is responsible for all the factors pulling the momentum index lower.