…at the UW-Madison. Ike Brannon spoke on behalf of the McCain-Palin campaign and Austan Goolsbee on behalf of the Obama-Biden campaign. Here’s the link to Proposals for Change (Adobe Flash required).
Author Archives: Menzie Chinn
Prospects for Output: The WSJ Survey
The WSJ just released its newest survey of economists’ views on the course of the economy. From the article:
On average, the 52 economists surveyed now expect gross domestic product to contract in the third and fourth quarters of this year, as well as the first quarter of 2009.
This is the first time that survey forecasts for those periods have turned negative. If those predictions bear out, it would mark the first time U.S. GDP — the total value of goods and services produced — has contracted for three consecutive quarters in more than a half century. Economists put the odds of recession in the next 12 months at 89%, up from 60% in last month’s survey.
Back to the Great Depression Debates
Or…Salt Water/Fresh Water Redux!
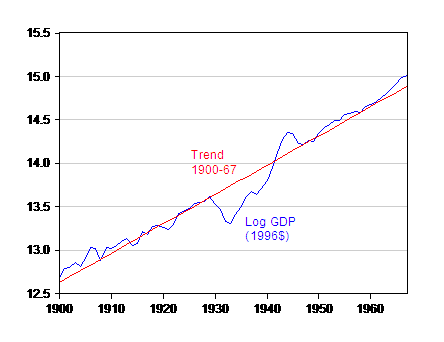
Figure 1: Log GDP (1996$), 1900-1967 (blue line), and linear trend (red line). Source: S.B. Carter, S.S. Gartner, M.R. Haines, A.L. Olmstead, R. Sutch, G. Wright, Historical Statistics of the United States, Millenial Edition (CUP, 2006).
The IMF’s Outlook
From Chapter 1 of the IMF World Economic Outlook, released today:
The world economy is now entering a major downturn
in the face of the most dangerous shock in mature
financial markets since the 1930s. Against an exceptionally
uncertain background, global growth projections
for 2009 have been marked down to 3 percent,
the slowest pace since 2002, and the outlook is subject
to considerable downside risks. The major advanced
economies are already in or close to recession, and,
although a recovery is projected to take hold progressively
in 2009, the pickup is likely to be unusually
gradual, held back by continued financial market
deleveraging. In this context, elevated rates of headline
inflation should recede quickly, provided oil prices stay
at or below current levels. The emerging and developing
economies are also slowing, in many cases to rates well
below trend, although some still face significant inflation
pressure even with more stable commodity prices.
The immediate policy challenge is to stabilize global
financial markets, while nursing economies through a
global downturn and keeping inflation under control.
Over a longer horizon, policymakers will be looking to
rebuild firm underpinnings for financial intermediation
and will be considering how to reduce procyclical
tendencies in the global economy and strengthen supplydemand
responses in commodity markets.
How Bad Will the Downturn Be? Stylized Facts
The IMF released several chapters of the World Economic Outlook; one chapter entitled Financial Stress and Economic Downturns provides some insights into the ramifications of the current financial turmoil.
Are We Still Sure We’re Not in a Recession? More on the Employment Situation
I hate to pile on, perhaps in a repetitive fashion given Jim’s post, but a mere three weeks ago, Donald Luskin was asserting “Things today just aren’t that bad.” And, pulling a comment out from mid-September, we have this definitive statement: “But in the final analysis let’s just stick to facts. We are not in a recession.”
“Do I Feel Lucky?”
Reader Bruce Hall inquires why Econbrowser has not weighed in on the rescue debate. First, I’ll observe there has been plenty of commentary on the web. But if compelled, then speaking only for myself, I think the members of Congress who voted against the plan the first time should, this time around, ask themselves this single question: “Do I Feel Lucky?” Those who are familiar with this quote will understand my meaning.
Chinese Trade: An Update
I was surprised by this item from the BBC:
Chinese trade surplus at new high
Wednesday, 10 September 2008
China’s trade surplus hit a monthly record of $28.7bn (£16.28bn) in August as the gap with the US and Europe widened, despite weaker world demand.
Last Quarter’s Fundamentals…
Weren’t as strong as some of us thought.
I was surprised; so were market observers. From Bloomberg:
U.S. Economic Growth Slower Than Initially Estimated (Update2)
By Timothy R. Homan
Sept. 26 (Bloomberg) — The U.S. economy expanded more slowly than previously estimated in the second quarter, showing consumer spending was weakening before the credit crisis intensified.
Peterson Institute for International Economics Joins the Blogosphere
From the Peterson Institute comes the “Real Time Economics Watch”. The latest posts are on how each crisis is different and yet the same [0], by Ted Truman, and the US/Japan parallels (or lack thereof) [1], authored by Adam Posen.
(The Peterson Institute doesn’t call it a weblog, but it seems like one…)